

Owning a home can be one of the biggest financial investments you make—and over time, that investment may also give you another financial resource: home equity . As you pay down your mortgage and your home's value changes, you may build equity that can potentially help finance certain expenses. For some homeowners, a home equity loan can provide funds for a major repair, a long-planned renovation, or another larger expense that would be difficult to cover all at once. But borrowing against your home is a significant financial decision. A home equity loan isn't simply extra money available to spend. Your home serves as collateral for the loan, making it especially important to understand what you're borrowing, why you're borrowing it, and how repayment will fit into your budget. Let's take a closer look at how home equity works, reasons homeowners may choose to use it, and the questions worth asking before you borrow. Start With the Basics: What Is Home Equity? Home equity is generally the difference between the current value of your home and the amount you still owe on loans secured by the property. For example, imagine your home is currently worth $300,000, and you owe $190,000 on your mortgage. $300,000 home value – $190,000 mortgage balance = $110,000 in home equity That doesn't necessarily mean you can—or should—borrow the full $110,000. The amount a homeowner may qualify to borrow depends on factors such as the property's value, outstanding mortgage balances, credit history, income, lender requirements, and the borrower's overall financial situation. A home equity loan allows a homeowner to borrow a specific amount of money using the home as collateral. The funds are generally received as a lump sum and repaid over a set period. The Consumer Financial Protection Bureau provides a helpful explanation of how home equity loans work and the responsibilities that come with borrowing against your home. Another option you may hear about is a home equity line of credit, or HELOC . Unlike a home equity loan, which typically provides the borrowed amount upfront, a HELOC is a revolving line of credit, allowing borrowers to draw funds as needed, subject to the terms of the account. The two products work differently, so it's important to understand which type of borrowing you're considering. Home Repairs: When the House Doesn't Wait Some home expenses are carefully planned years in advance. Others show up as a dripping ceiling, a cold house in January, or a water heater that suddenly decides it has reached retirement age. Major repairs are one reason homeowners may explore their home equity options. These could include: Roof replacement or significant roof repairs Heating or air-conditioning system replacement New windows Plumbing repairs Electrical work Water or structural damage Septic or sewer repairs Other major systems needed to keep the home safe and functional Imagine, for example, that several projects begin to overlap. A homeowner learns that a major HVAC replacement will cost approximately $12,000 and discovers another $6,000 of necessary plumbing work. Rather than looking only at each expense separately, the homeowner now has an estimated $18,000 home repair project to consider. That doesn't automatically make a home equity loan the right solution. It does, however, illustrate why some homeowners look into home equity financing when an expense is too large to comfortably absorb with regular monthly cash flow or available savings. Before borrowing, it's helpful to get detailed estimates and understand the full scope of the work. Building some room into the project budget for unexpected expenses may also help prevent a project from becoming financially strained midway through. Home Improvements: Investing Back Into Your Space Not every home project begins with something breaking. Maybe the kitchen has been on your wish list since you moved in. Perhaps an unfinished basement could give your family badly needed living space. Or your home may need modifications that make it safer or more accessible as your family's needs change. Homeowners may consider home equity financing for improvements such as: Kitchen renovations Bathroom renovations Finished basements Additions Flooring Energy-efficiency improvements Exterior improvements Accessibility modifications Aging-in-place updates Larger renovation projects can involve several individual expenses. For example, suppose a homeowner is considering: Kitchen updates: $18,000 Flooring: $7,000 Electrical improvements: $4,000 Total planned project: $29,000 Looking at the entire $29,000 project instead of the individual pieces can help the homeowner decide how much they actually need to finance—and whether the project makes sense within their overall budget. It's also worth separating "What would I like to do?" from "What does the house actually need?" There is nothing wrong with improving a home simply because you want to enjoy it more. But because a home equity loan is secured by your property, the reason for borrowing deserves careful consideration. And although some improvements may increase a home's value, homeowners shouldn't assume that every dollar spent on a renovation will be recovered when the property is eventually sold. Larger Planned Expenses Home equity loans aren't limited strictly to home repairs and renovations. Depending on the lender and loan terms, funds may be available for other purposes as well. A homeowner might explore home equity when faced with a larger planned expense that would otherwise require a significant amount of cash at once. The important word here is consider . Just because home equity is available doesn't mean borrowing against your home is automatically the best way to pay for every large expense. Remember: a home equity loan is secured by your house. The Federal Trade Commission and the National Credit Union Administration's MyCreditUnion.gov both emphasize that borrowers should understand the risks, costs, and repayment obligations involved when using their homes as collateral. That makes it important to compare your options. Ask yourself: Is this expense necessary or optional? How long will I benefit from what I'm financing? Are there other ways I could pay for part or all of the expense? What would happen to my budget if my financial circumstances changed? Sometimes the best decision is to borrow. Sometimes it's to borrow less. And sometimes it's to wait, save, or explore another financing option. The goal should be to choose the option that makes sense for your circumstances—not simply choosing the largest amount available. Think Beyond the Monthly Payment When comparing borrowing options, it's easy to focus on one number: "What will my payment be?" The payment absolutely matters. It needs to fit comfortably into your monthly budget, but it shouldn't be the only number you consider. Suppose two loan options finance the same project. One provides a smaller monthly payment by stretching repayment over a much longer period. The smaller payment might initially seem more attractive, but a longer repayment term can also mean paying interest for a longer period. That's why it's important to consider the loan as a whole. Look at factors such as: Amount borrowed Interest rate Annual Percentage Rate (APR) Loan term Monthly payment Fees or closing costs Total amount repaid over the life of the loan The CFPB specifically recommends looking beyond the monthly payment when evaluating home equity borrowing because home equity loans may also involve upfront fees and other costs. Here's another simple example. Imagine you're planning a $30,000 renovation , but you already have $8,000 saved specifically for the project. Rather than automatically financing all $30,000, you might consider whether using some savings and borrowing a smaller amount makes sense: Estimated project: $30,000 Available project savings: $ 8,000 Potential amount to finance: $ 22,000 T hat doesn't mean using your savings is always the correct choice—you may need to preserve an emergency fund or other reserves. It simply illustrates why determining how much you actually need to borrow can be just as important as determining how much you qualify to borrow. Six Questions to Ask Before Borrowing Against Your Home Before applying for a home equity loan, give yourself a little homework. 1. What is the project expected to cost? Whenever possible, get detailed quotes or estimates. Knowing whether you're planning for a $10,000 project or a $35,000 project makes a major difference. And don't forget the expenses surrounding the project—not just the headline price. 2. How much equity do I have? Start with an estimate of your home's current value and subtract what you owe on your mortgage and other property-secured loans. Keep in mind that this gives you an estimate of your equity; it doesn't determine the amount you will ultimately be able to borrow. 3. How much do I actually need? There's a difference between how much you can borrow and how much you need. Start with the expense itself, then consider available savings and other resources before determining your requested loan amount. 4. What payment fits comfortably into my budget? "Technically affordable" and "comfortably affordable" aren't always the same thing. Consider your regular obligations as well as less predictable expenses. A payment that leaves absolutely no breathing room in the household budget can become stressful when the car needs repairs, property taxes change, or another unexpected expense arrives. 5. How long will I be paying for it? Think about the relationship between the expense you're financing and the length of the loan. A lower payment spread over a longer term may sound appealing, but consider the total borrowing cost and how long you want the obligation to remain in your budget. 6. Is borrowing against my home appropriate for this expense? This may be the most important question of all. With a home equity loan, your home is collateral . If you are unable to repay a home equity loan according to its terms, foreclosure is a potential consequence. That doesn't mean homeowners should be afraid of home equity borrowing. It means the decision deserves the same thoughtful approach you'd give any other major financial commitment. Put Your Home Equity to Work Thoughtfully Your home can represent much more than the place where you live. After years of mortgage payments and homeownership, the equity you've built may provide another financial option when a major expense comes along. Whether you're replacing a roof, updating an aging kitchen, improving your home's accessibility, or planning another expense, the first question shouldn't necessarily be, "How much can I borrow?" A better place to start may be: "What am I trying to accomplish, what will it really cost, and what borrowing option fits comfortably into my financial picture?" Those are questions worth talking through with someone before making a decision. Talk With Superior Credit Union At Superior Credit Union , we're here to help you understand your options—not simply hand you a loan. If you're considering a home repair, renovation, or another larger expense, our team can help you learn more about available home equity options, how the borrowing process works, and what factors you should consider before moving forward. Learn more about Superior Credit Union home equity options and talk with our team about what may fit your situation. Additional Home Equity Resources For homeowners who would like to do some additional research, these independent resources are a good place to start: Consumer Financial Protection Bureau: Learn what a home equity loan is and how home equity loans and HELOCs differ. CFPB: What Is a Home Equity Loan? MyCreditUnion.gov: The National Credit Union Administration's consumer resource explains home equity loans, lines of credit, and factors borrowers should consider. MyCreditUnion.gov: Home Equity Loans and Lines of Credit Federal Trade Commission: Review consumer information about borrowing against the equity in your home, including costs and potential risks. FTC: Home Equity Loans and Home Equity Lines of Credit Internal Revenue Service: For questions regarding the possible tax treatment of mortgage or home equity interest, review IRS guidance and speak with a qualified tax professional. IRS: Mortgage Interest Deduction Information
Why Opening a Minor Account Can Help Kids Learn About Money
What to Consider Before Financing a Vehicle
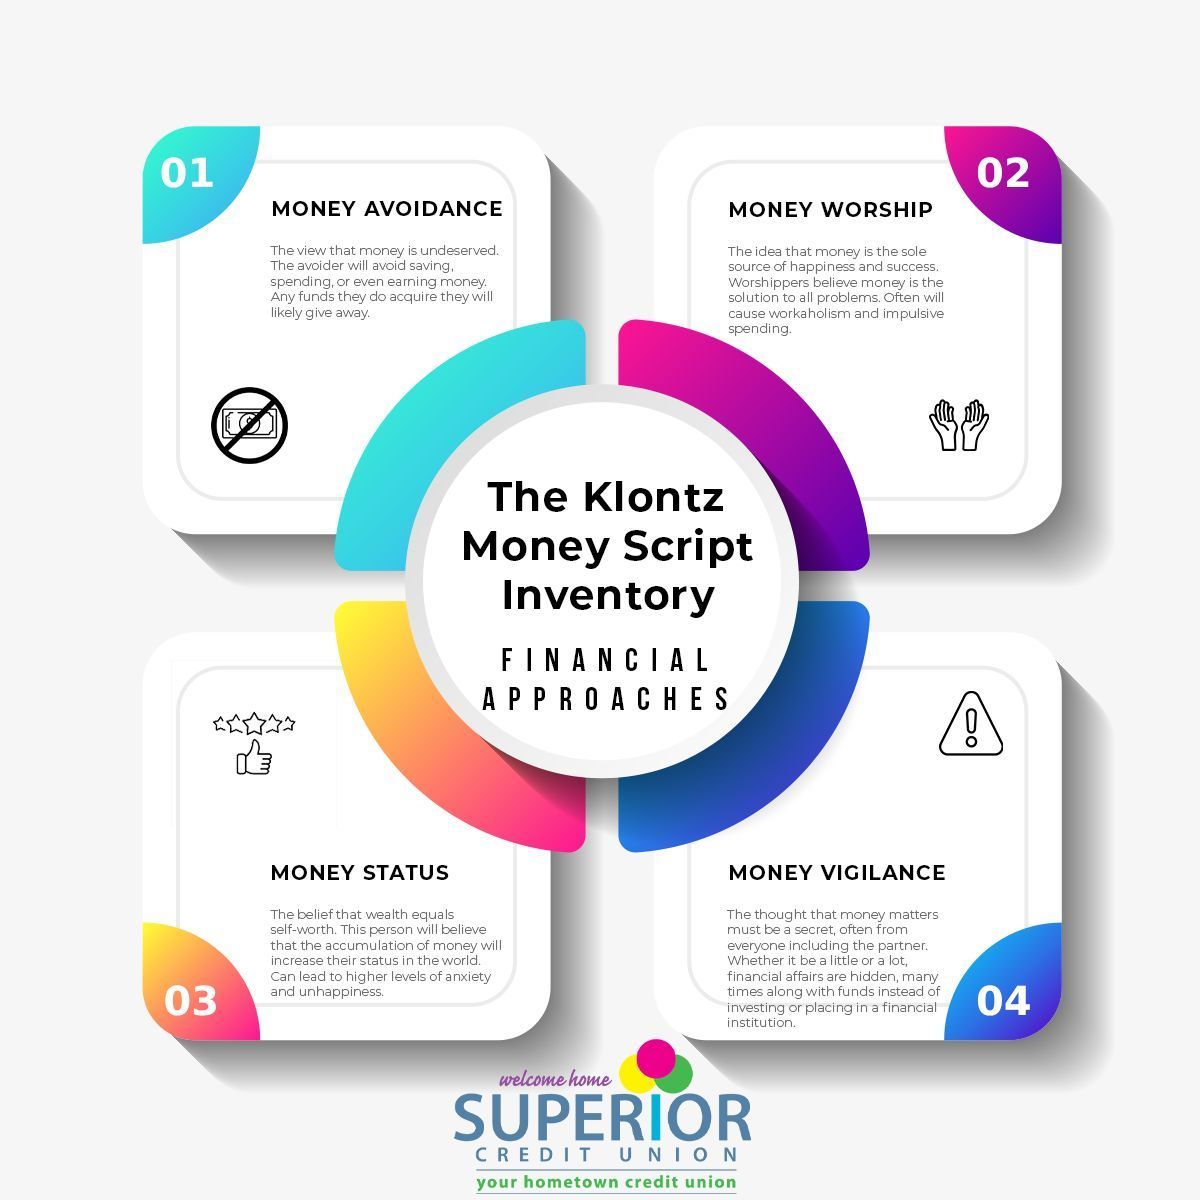
The Klontz Money Script Inventory outlines the different ways people look at money and how that informs their saving and spending habits.
Debt Snowball and Debt Avalanche are two different approaches to effective debt management and debt payoff. Each offering different methods to manage overwhelming debt.
Get to know the in's and out's of becoming or electing a Power of Attorney for your financial future.
Buying a used car can be a very stressful time. Read this blog and be prepared when shopping for your next vehicle. Buying used has benefits most don't realize!
Use this blog as a guidepost to filing your Federal, State, and Local taxes every year. Don't forget a thing with our tips and reminders!
Tips to recognize and avoid romance scams and how to protect your finances from exploitation.
Looking for free or low cost adventures for your family in Montgomery County, PA? Click here to see the list of fun activities we compiled just for you!
Explore tried and true ways to start saving money.
Budgeting can be difficult, but with this blog you will be quickly on your way to saving for your next big trip or purchase!
Planning for expenses that change from month to month can be challenging. Take a look at these tips to make it a little easier.
Knowing which expenses are a regular part of your budget is essential to successfully managing your money. Learn what fixed expenses are, how to track them, and how much room in your budget you should allocate for them.
Read to discover what red flags your budget may have, and how to easily fix them to get you back on the path to financial wellness.
Gift card scams are becoming BIG problem in the fraud world. Here's what you need to know and how to avoid a gift card scam.
The best way to protect your information is multiple layers of authentication. Learn about Two Factor Authentication (2FA) and how to make it work for you
Take a look at all your digital information out there, and asess your fraud risk, then use this checklist to get your accounts secured with our Fraud Prevention Checklist
Four simple tips that will make your black friday shopping trip easier, more fun, and less stressful.
Traveling is stressful enough, without fraud slipping in and ruining your day. Plan ahead and read this to learn the latest travel scams and how to avoid them.
Recognizing the traits of the most common scams is the first step in protecting yourself against fraud.
Learn the tips to differentiate between a legitimate website and a fake or imposter one.
The basics to protecting your accounts and personal information against fraud are easy!
If you are new to the concept of financial fraud and scams, read this to "get in the know" and become an expert in protecting your own finances.
Getting to know credit card interest
When it comes time to choosing a credit card, there are many factors that must be considered. In a few easy steps we explain how to find the best fit for your spending habits and financial goals.
When choosing a credit card, all the new vocabulary can be intimidating. Here is a comprehensive list of concepts you should know before opening a credit card.
They say money creates happiness, but is that true? Take a look at five financial bad habits that you may be doing already, and how to break them.
Some questions you can ask yourself when considering opening a Certificate of Deposit.
Here are the 5 things you should know when researching a financial institution to open a checking account.
Vacations take time to plan, but why don't we take time to save for them also? Here are four reasons why you should start saving NOW for your next getaway!
Putting money away in a savings account is a good thing, however interest rates on a traditional savings are often very low. Here are different ways you can turn those pennies into dollars!